

Profit and Loss:
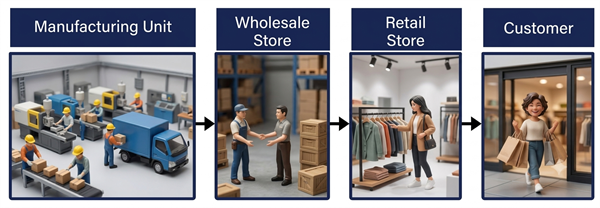
1. Understanding Cost Price, Selling Price and Marked Price
When we buy and sell goods, different prices are used to describe the transaction.
Cost Price (CP) :
The cost price is the amount paid by a shopkeeper to purchase an item.
Selling Price (SP) :
The selling price is the amount for which the shopkeeper sells the item to the customer.
Marked Price (MP) :
The marked price is the price written or displayed on an item before a discount is given.
2. Profit :
A shopkeeper makes a profit when the selling price is greater than the cost price.
3. Loss :
A shopkeeper makes a loss when the selling price is less than the cost price.
The amount of profit alone does not tell us how large the profit is compared with the money invested.
For this, we use profit percentage.
Profit percentage is calculated with respect to the cost price.
\(\text{Profit Percentage} = \frac{\text{Profit}}{\text{CP}} \times 100\)
5. Loss Percentage:
Loss percentage is also calculated with respect to the cost price.
\(\text{Loss Percentage} = \frac{\text{Loss}}{\text{CP}} \times 100\)
6. Finding the Selling Price When Profit Percentage is Given:
Suppose the cost price and profit percentage are known.
If the profit is \(r \%\), then the selling price is
\(\text{SP} = \text{CP} + \frac{r}{100} \times \text{CP}\)
7. Finding the Selling Price When there is a Loss:
If an item is sold at a loss of \(r \%\), then the selling price is \(100 - r \%\) of the cost price.
\(\text{SP} = (100 - r) \%\) of \(\text{CP}\)
8. Marked Price and Discount:
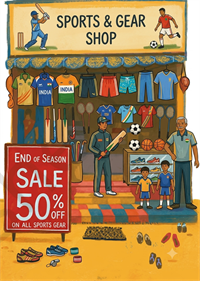
A shopkeeper may write a price on an item and then offer a discount to attract customers.
The price written on the item is called the marked price.
- A discount is the reduction given on the marked price.
\(\text{Discount} = \text{Marked Price} - \text{Selling Price}\)
- The discount percentage is calculated with respect to the marked price:
\(\text{Discount Percentage} = \frac{\text{Discount}}{\text{MP}} \times 100\)
Important!
Connecting Profit, Loss and Discount
A discount is calculated from the marked price, whereas profit or loss is calculated by comparing the selling price with the cost price.
Therefore, these percentages may have different bases.
For example:
- Discount Percentage --------> based on marked price
- Profit Percentage ----------> based on cost price
- Loss percentage ------------> based on cost price
Gross Profit and Net Profit:
Gross Profit:
Gross profit is the difference between sales revenue and the cost of purchasing the goods sold.
\(\text{Gross Profit} = \text{Revenue} - \text{Cost of Goods}\)
Net Profit:
A business may have other expenses apart from purchasing goods.
For example:
- transport charges
- electricity expenses
- employee salaries
- rent
- packaging expenses
After subtracting these expenses from gross profit, we obtain the net profit.
\(\text{Net Profit} = \text{Gross Profit} - \text{Other Expenses}\)
Taxes:
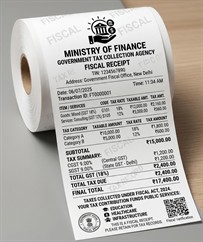
A tax is an amount collected by the government from individuals or businesses according to specified rules.
Tax rates are often expressed as percentages.
GST - Goods and Services Tax
GST stands for Goods and Services Tax.
When GST is charged on a taxable price, the GST amount is calculated as a percentage of that price.
\(\text{GST Amount} = \frac{\text{GST Rate}}{100} \times \text{Taxable Price}\)
The final amount paid by the customer is:
\(\text{Final Price} = \text{Taxable Price} + \text{GST}\)
Important!
Recall:
- CP tells us what the seller paid.
- SP tells us what the customer pays for the item before any separately added tax.
- MP is the price displayed before discount.
- Profit occurs when \(\text{SP} > \text{CP}\)
- Loss occurs when \(\text{SP} < \text{CP}\)
- Profit and loss percentages use \(\text{Cost Price}\) as the base.
- Discount percentage uses \(\text{Marked Price}\) as the base.
- A tax rate is a percentage of the amount on which the tax is charged.
- GST is added to the applicable taxable price.